
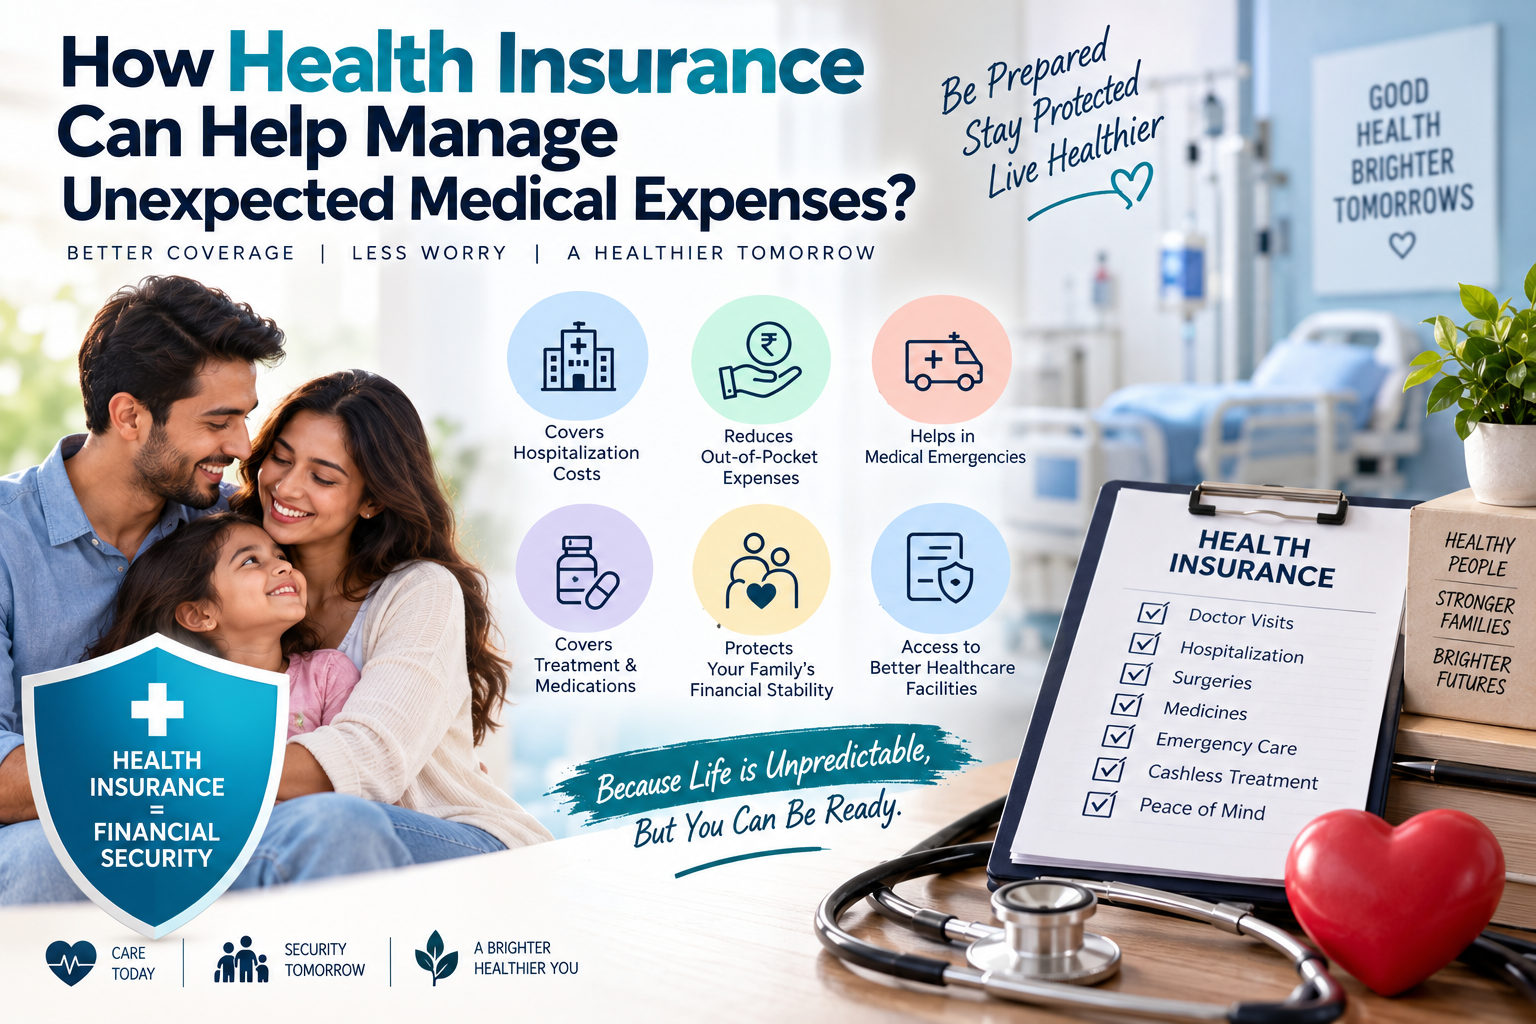
Medical expenses can arise unexpectedly and place significant pressure on a household’s finances. An accident, sudden illness, emergency procedure, hospitalization, or ongoing treatment can result in costs that are difficult to manage through regular income and savings alone. Health insurance is designed to provide financial protection against certain covered healthcare expenses, helping individuals and families manage the economic impact of medical care.
The exact protection provided depends on the policy, insurer, location, coverage limits, exclusions, deductibles, and other terms. Understanding these details is essential before purchasing a plan.
Provides Financial Protection During Medical Emergencies
Medical emergencies often require immediate attention, leaving little time to plan financially. Hospitalization, diagnostic tests, surgery, medicines, and other services can add up quickly.
A health insurance policy may cover eligible expenses according to its terms. Instead of paying the entire covered cost from personal savings, the insured person may receive financial assistance through the policy.
This can reduce the risk of a single medical event causing a major disruption to household finances.
Helps Protect Personal Savings
Many people save money for education, home purchases, retirement, travel, or other long-term goals. A large unexpected medical bill can force them to use some or all of those savings.
Health insurance can help limit the amount of money that needs to come directly from personal funds when covered healthcare costs arise. This can allow families to preserve more of their savings for their intended purposes.
Supports Access to Healthcare
Financial concerns can sometimes cause people to delay seeking medical attention. Having health insurance may make individuals more comfortable seeking eligible healthcare services when they need them.
Depending on the policy, coverage may include hospitalization, certain diagnostic procedures, specialist consultations, medicines, or other healthcare services. Consumers should always check the specific benefits rather than assuming every medical expense is covered.
Can Help With Hospitalization Costs
Hospital stays can involve multiple expenses beyond the basic room charge. Treatment may include physician fees, diagnostic tests, surgery, nursing services, medicines, and other related costs.
A suitable health insurance policy can provide coverage for eligible hospitalization expenses according to its conditions and limits. Understanding room-rent restrictions, deductibles, co-payments, exclusions, and coverage limits can help policyholders avoid unexpected financial obligations.
Offers Support for Planned Treatment
Not all healthcare expenses occur during emergencies. Some treatments and procedures can be planned.
Certain insurance policies cover eligible planned treatments, subject to specific requirements. Policyholders may need to use an approved network, obtain authorization, or meet other conditions before receiving coverage.
Reviewing these requirements before planned treatment can make the process smoother.
Network Providers Can Simplify Payments
Many insurers work with networks of hospitals and healthcare providers. Depending on the policy, treatment received through an eligible network provider may allow for direct settlement between the insurer and healthcare facility for covered expenses.
This can reduce the amount a policyholder needs to arrange immediately. However, patients may still be responsible for deductibles, co-payments, non-covered services, or expenses exceeding policy limits.
Provides Family-Wide Protection
Families may choose policies that cover multiple members under one arrangement. Such coverage can provide financial protection when different family members require medical care.
Family circumstances can change over time, so it is important to periodically review whether the policy’s coverage remains appropriate for household needs.
Helps Manage Rising Healthcare Costs
Healthcare costs can vary significantly depending on the treatment, provider, location, and complexity of the condition. Medical inflation can also make future healthcare expenses difficult to predict.
Insurance can help individuals prepare for these costs by transferring some financial risk to the insurer, subject to the policy’s terms and limits.
Understanding Policy Terms Is Essential
Buying health insurance should not be based only on the premium. Consumers should examine the coverage amount, waiting periods, exclusions, deductibles, co-payments, claim procedures, network providers, renewal conditions, and limits.
It is also important to disclose relevant information accurately when applying. Misunderstanding policy conditions can create difficulties when filing a claim.
Building a Broader Financial Safety Net
Health insurance works best as part of a broader financial plan. An emergency fund can help cover expenses that insurance does not pay, while savings and investments can support longer-term goals.
Combining different forms of financial preparation can make households better equipped to handle unexpected situations.
Conclusion
Health insurance can help individuals and families manage the financial impact of unexpected medical expenses. It may provide protection against eligible hospitalization and treatment costs, reduce pressure on personal savings, and make healthcare expenses more predictable. Because coverage varies considerably between policies, consumers should carefully review benefits, exclusions, limits, and out-of-pocket responsibilities before choosing a plan. With appropriate coverage and complementary savings, health insurance can become an important part of a family’s financial protection strategy.